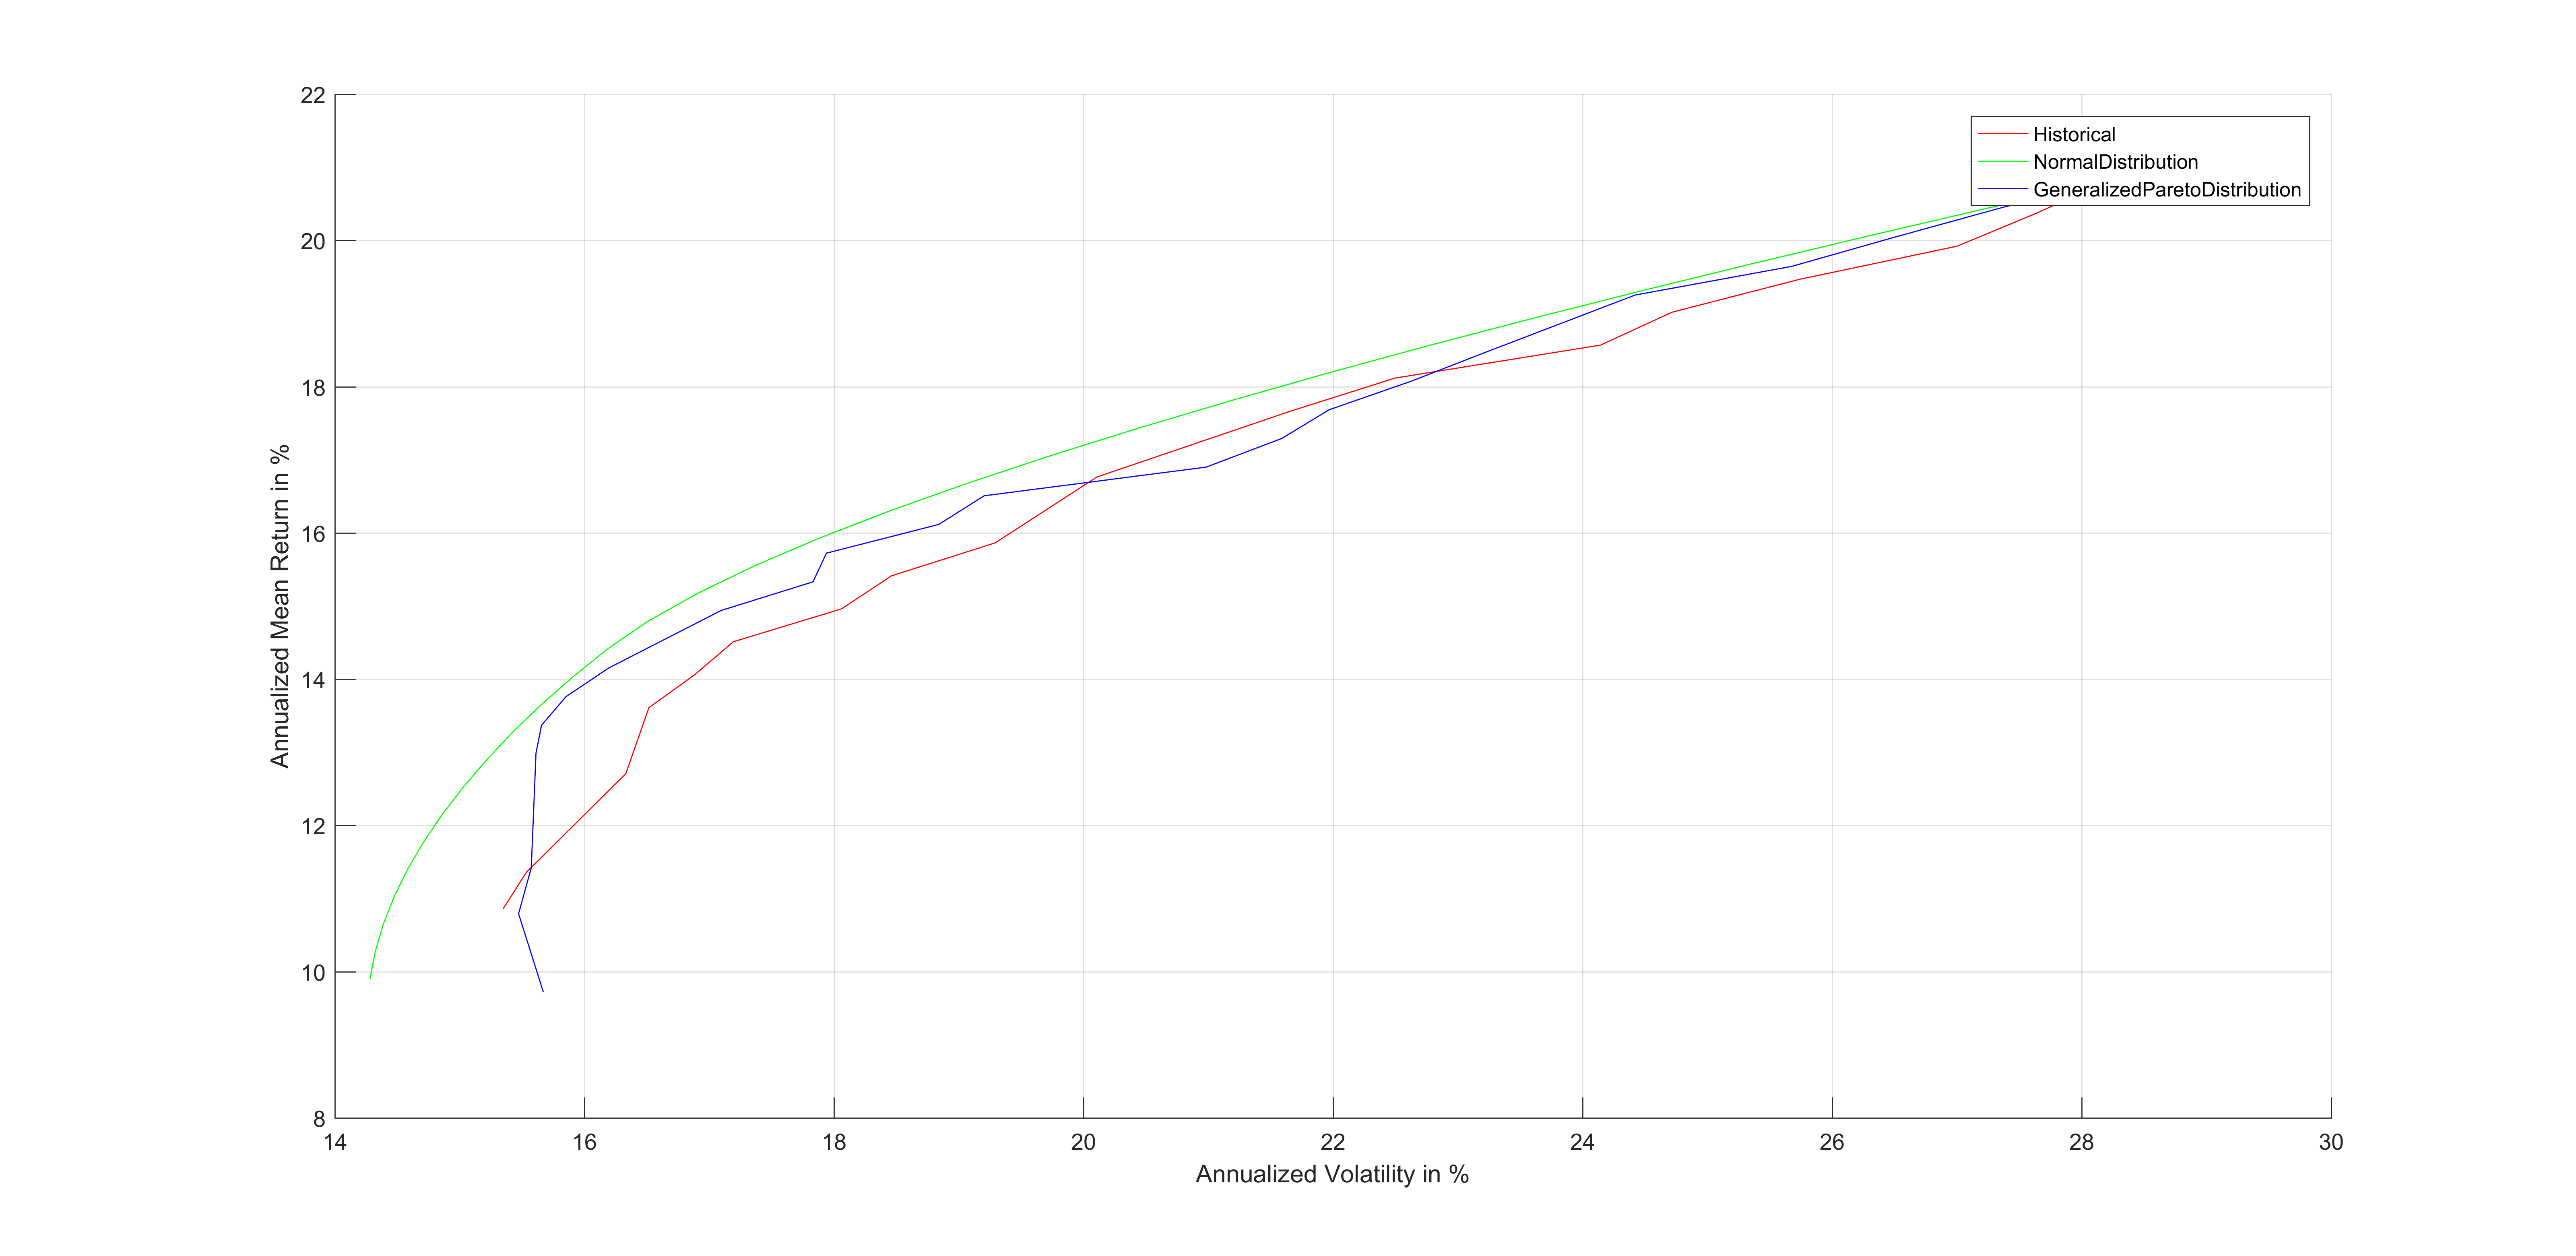
Mean-ValueAtRisk Optimization
This library contains MVaRP object (MeanValueatRiskPortfolio).

You are now following this Submission
- You will see updates in your followed content feed
- You may receive emails, depending on your communication preferences
Cite As
Riccardo Brignone (2026). Mean-ValueAtRisk Optimization (https://in.mathworks.com/matlabcentral/fileexchange/59630-mean-valueatrisk-optimization), MATLAB Central File Exchange. Retrieved .
Categories
Find more on Portfolio Optimization for Asset Allocation in Help Center and MATLAB Answers
General Information
- Version 1.0.0 (1.06 MB)
MATLAB Release Compatibility
- Compatible with any release
Platform Compatibility
- Windows
- macOS
- Linux
| Version | Published | Release Notes | Action |
|---|---|---|---|
| 1.0.0 | Icon Added |

